You helped build something meaningful. Now your company is going public, and the equity you’ve watched for years could create opportunities you once put on hold.
Maybe that means buying your first home, finding more space for your family, helping your parents, or creating the freedom to work differently.
It’s exciting. It also raises a practical question: What should you do first?
My perspective as a Bay Area real estate professional is to start with a plan before choosing a property. A home should support your financial future and the life you want to build.
John Saddi helps buyers evaluate homes throughout San Francisco and San Mateo County, including South San Francisco, San Bruno, Millbrae, Burlingame, and San Mateo.
First, separate your stock value from your available money
An IPO does not automatically put cash in your bank account. Your equity may include vested shares, unvested awards, or stock options that require an exercise payment. Lockup agreements and company trading restrictions can also limit when you may sell. Review your own documents rather than assuming a coworker’s timeline applies to you. Investor.gov explains IPO lockup agreements.
Before making a major commitment, answer three questions:
- What do I own today?
- What am I permitted to sell, and when?
- What could remain after exercise costs, taxes, and other obligations?
That final number is the starting point for a spending plan. The value displayed in your stock account is not necessarily your homebuying budget.
1. Build your team before making irreversible decisions
You don’t have to become an expert in equity compensation overnight. You do need professionals who understand how the decisions fit together.
| Professional | Questions they can help answer |
|---|---|
| CPA experienced in equity compensation | What taxes could different exercise and sale decisions create? |
| Financial planner or investment adviser | How should this wealth support my goals, spending, and investment plan? |
| Estate-planning attorney | Do my estate documents and ownership arrangements need updating? |
| Mortgage lender familiar with equity compensation | What income and assets will qualify, and what documentation is required? |
| Local real estate professional | Which homes fit my priorities, budget, and ownership costs? |
Ask about relevant experience, fees, conflicts of interest, and whether an adviser acts as a fiduciary throughout your relationship. Coordinating the team can help prevent one decision from undermining another.
2. Estimate taxes before allocating the proceeds
There is no universal “IPO tax rate.” Your equity type, cost basis, exercise history, holding periods, and personal circumstances matter.
For example, exercising incentive stock options can create alternative minimum tax exposure even before you sell the shares. Nonqualified options follow different rules. California adds its own considerations. See the IRS stock-options overview and California’s stock-option guidance.
Ask your CPA to estimate your remaining liability after withholding and any payments already made, including when additional payments may be due.
Do this before treating the proceeds as available for a down payment, gifts, or investments.
Also ask whether the funds reserved for taxes should be held separately from money you plan to spend. A clear separation can make it easier to avoid committing the same dollars twice.
3. Decide what you want the money to change
Before comparing investments or neighborhoods, write down what matters most.
Would this money help you:
- Build financial security?
- Reduce expensive debt?
- Buy a home you expect to enjoy for years?
- Fund education or support family?
- Gain flexibility to change jobs?
- Strengthen retirement savings?
- Support charitable causes?
You can celebrate the milestone while still making deliberate choices. Setting a celebration budget may help you enjoy the achievement without allowing a series of purchases to become a permanent increase in expenses.
The right plan should reflect your priorities—not the purchases your coworkers are making.
4. Review how much depends on one company
Your employer may already provide your salary, benefits, and future equity awards. If it also represents most of your investments, several parts of your financial life depend on the same business.
That is a reason to discuss concentration risk with your adviser. Diversifying can spread investment risk, although it cannot eliminate losses. A sale plan should account for taxes, trading restrictions, and your goals.
One useful discussion starter is: If I received this amount in cash today, how much would I choose to invest in my employer?
Your answer can help clarify your comfort level without requiring you to predict the stock’s highest price.
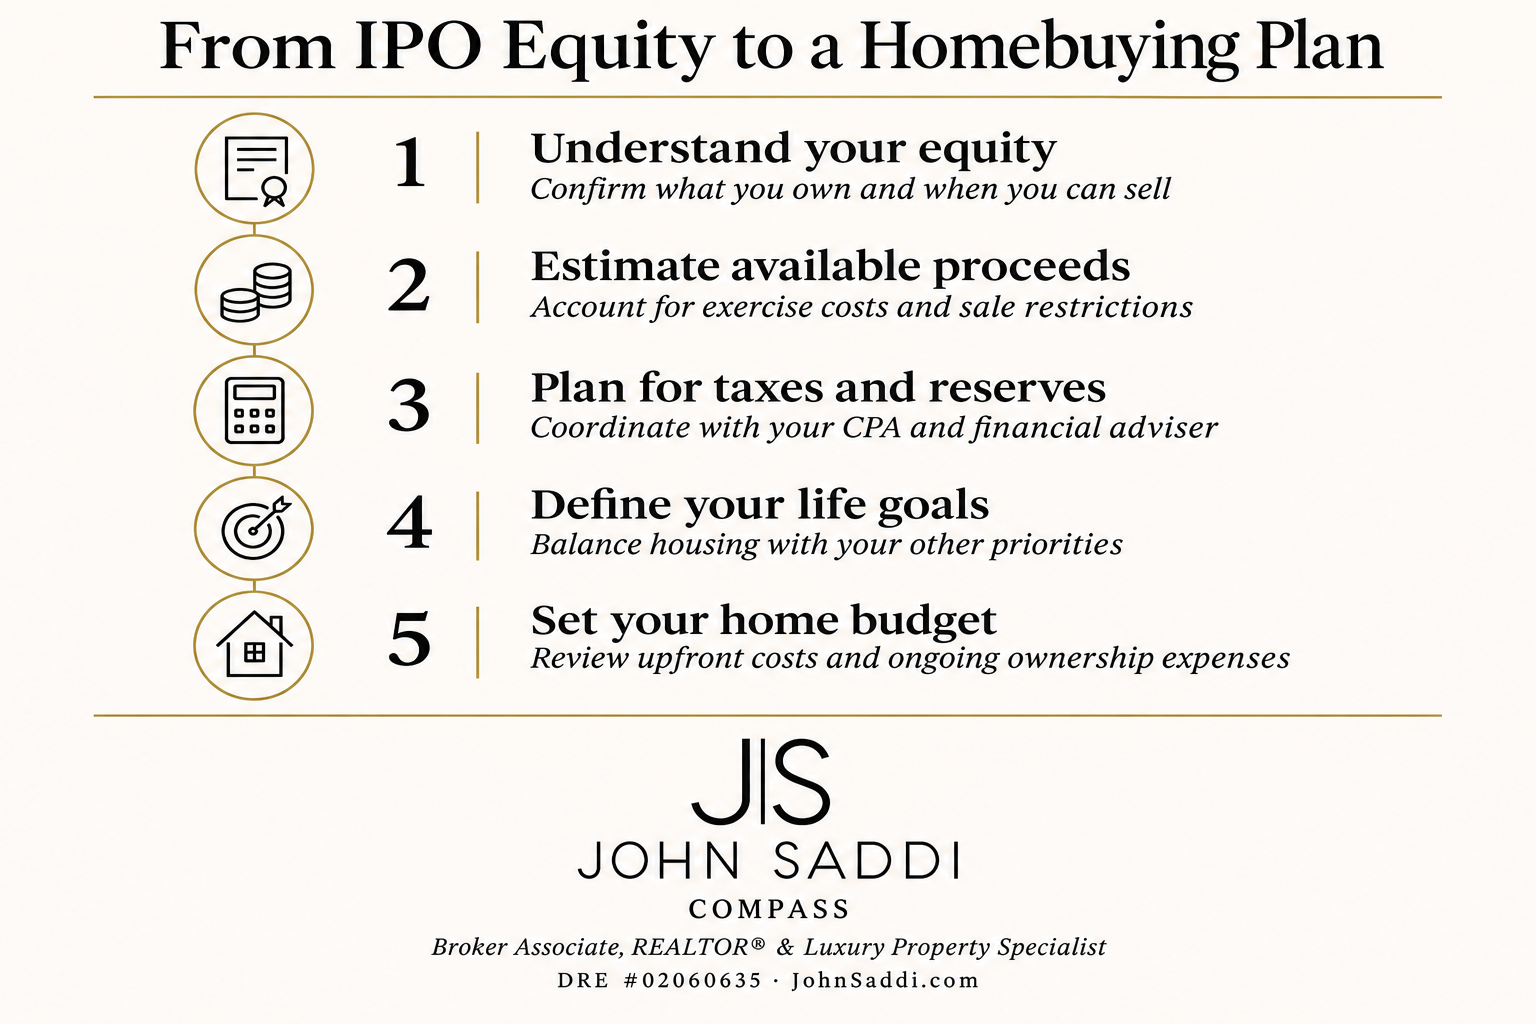
“When an IPO changes your financial picture, start by deciding what you want homeownership to make possible. Build your budget around accessible funds, a tax plan, and a monthly payment you can comfortably sustain.”
5. If you want to buy a Bay Area home, establish two budgets
I recommend separating these decisions:
Your purchase budget: How much can you commit to the down payment and closing while preserving taxes, reserves, and other goals?
Your monthly ownership budget: What ongoing payment feels sustainable without depending on a rising stock price or another large equity payout?
Include more than the mortgage:
- Property taxes and homeowners insurance.
- HOA dues and potential assessments, where applicable.
- Maintenance, repairs, and utilities.
- Immediate improvements and moving expenses.
- Cash you want available after closing.
A larger down payment can reduce borrowing, but it also leaves less money available elsewhere. Paying cash and financing each involve tradeoffs worth reviewing with your lender and financial adviser.
6. Ask your lender how equity compensation will be evaluated
Having substantial assets and qualifying for a particular mortgage are related but different questions.
For loans following Fannie Mae guidelines, restricted-stock income has specific documentation and calculation requirements. Your lender’s program—including a jumbo or portfolio loan—may have different rules.
Before shopping, ask:
- Which parts of my compensation can count as qualifying income?
- How will you evaluate my vesting and distribution history?
- What records will you need for stock sales and transferred funds?
- When must my down payment be accessible?
- What reserves must remain after closing?
- How would a job change affect approval?
Get these answers before making an offer with a closing deadline. For more questions to bring to your lender, read Can You Use RSUs to Buy a Home in San Francisco?
7. Choose a home around your life, not IPO headlines
A successful IPO may change your options. It does not make every home a good purchase or guarantee future appreciation.
In San Francisco and San Mateo County, compare properties at the neighborhood and building level. Think about your commute, preferred layout, outdoor space, maintenance tolerance, and how long you expect the home to meet your needs.
For a condominium, review the association’s finances, insurance, inspection reports, and planned projects. For a single-family home, understand the inspection findings and likely repair costs.
The goal is to buy a home that still feels comfortable if your circumstances change.
I would rather help you establish that comfort level early than have you discover it after you are in contract.
Your first steps after an IPO
- Gather your equity documents and confirm sale restrictions.
- Have your CPA model taxes and payment deadlines.
- Define your priorities with your financial adviser.
- Establish an accessible homebuying budget and reserves.
- Confirm financing before committing to a purchase.
- Compare homes based on their condition, location, and total ownership costs.
You can begin learning about neighborhoods before you are ready to buy. Researching the market does not require rushing into a transaction.
Thinking about buying a home after your company goes public?
An IPO can create room to make a meaningful change. Whether you’re considering your first home, a move within the Bay Area, or simply exploring your options, I can help you understand the real estate side of the decision.
We can discuss neighborhoods, compare properties, and build a search around the budget you establish with your financial and lending team.
Explore my Bay Area buyer resources and local market reports, or schedule a conversation.
John Saddi
Broker Associate, REALTOR® & Luxury Property Specialist at Compass
650-291-2174 · john@johnsaddi.com
DRE #02060635
This article provides general educational information, not individualized investment, tax, legal, or lending advice. Consult qualified professionals about your circumstances.