Equity compensation · San Francisco homebuyers
RSUs can help some buyers qualify for a mortgage or fund a down payment, but your grant value is not automatically qualifying income or available cash. Before setting a San Francisco home budget, ask your lender to review your actual vesting history, award terms, bonuses, and loan program.
If you work in tech, the compensation number on your offer letter may include salary, an annual bonus, and equity that arrives on a different schedule. Turning that package into a homebuying plan takes more than dividing the headline number by twelve.
This guide is for buyers considering San Francisco, South San Francisco, and Peninsula communities such as San Mateo, Burlingame, and Millbrae. It helps you prepare for a lender conversation, rather than estimate a guaranteed loan amount.
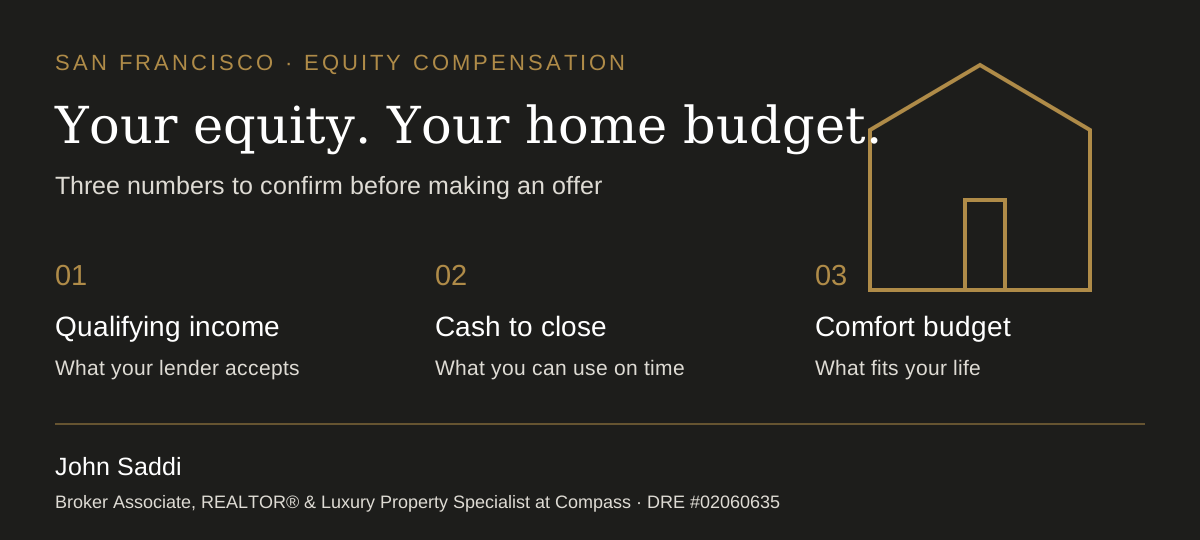
Start with three numbers, not one compensation total
Qualifying income
The income your lender accepts when reviewing the mortgage. Ask for the approved monthly breakdown of salary, bonus, and equity.
Cash to close
Funds you can actually use for your deposit, down payment, and closing costs by their deadlines.
Your comfort budget
The payment you can support after taxes, savings, family expenses, and a realistic buffer for variable compensation.
Two buyers with the same headline compensation can have different financing options. One may have an established public-company vesting record; another may hold private-company awards that are not readily saleable. A lender needs the details behind the totals.
Can RSU income count toward a mortgage?
Under Fannie Mae’s restricted-stock guidance, eligible awards must already have vested and been distributed without restrictions. Documentation includes publicly traded stock, vesting schedules, and evidence of distributions. Restricted-stock sign-on bonuses are excluded from qualifying income under this guidance. Share-based income uses a 200-day average stock price with historical distributed shares, rather than today’s share price alone. Review Fannie Mae’s RSU guidance.
Ask which rules apply to your actual loan. A jumbo or portfolio mortgage may follow different lender criteria. Approval depends on the complete application; the agency guidance is not a promise that every lender will accept your equity.
Why vesting history and bonuses matter
Fannie Mae distinguishes time-based from performance-based awards. Time-based RSUs require at least 12 months of history with the current employer; performance-based awards have different history criteria. Continuance requirements also distinguish recurring and one-time awards. Ask your lender to identify your category and explain its calculation before relying on the income. Source: restricted-stock income requirements.
For bonuses, Fannie Mae recommends a two-year history, with certain shorter histories of at least 12 months potentially acceptable. Lenders evaluate payment frequency and income trends; declining income requires further review. Source: bonus income guidance.
Ask specifically about a recent job change, a new grant, a lower bonus, or an award that ends soon. A refresh grant on a dashboard and a distribution already received are different pieces of evidence.
Using equity for your down payment is a separate question
Ask what the lender needs to verify ownership, value, and—when applicable—liquidation and receipt of investment funds. Fannie Mae has separate asset rules for stocks and other investments. Review the asset documentation guidance.
Build your purchase timeline around cash availability. A future vest, expected IPO, or possible tender offer should not be treated as closing cash without a confirmed path to usable funds. Discuss trading windows, settlement and transfer timing, and tax cash needs with the relevant professionals before committing to a sale or purchase deadline.
Ten questions to ask your lender before touring homes
- Which loan program are you evaluating, and does it accept my type of equity compensation?
- What monthly amount will you accept from salary, bonus, and RSUs separately?
- How much vesting history do you require for my award type and employer?
- Which stock-price measure and averaging period will you use?
- How will a recent job change, declining share price, or lower bonus affect qualification?
- Do you need future vesting or award-continuance documentation?
- How will you treat private-company equity, options, or restricted-stock sign-on awards?
- What evidence is needed if I sell shares to fund the purchase, and when must cash be available?
- How much must remain in reserves after closing, and which assets qualify?
- Has an underwriter reviewed my compensation documents, and what conditions remain?
Request a written income breakdown and an explanation of outstanding conditions. Compare lenders using the same documents and proposed purchase, rather than relying only on a verbal maximum budget.
Documents to gather for the first conversation
- Recent paystubs and W-2s for the periods the lender requests.
- Grant agreements and schedules showing past and future vesting.
- Equity-account statements and distribution records.
- Bonus history and relevant employment documents.
- Bank and brokerage statements for down payment and reserves.
- Evidence of any planned stock sale and transfer, when requested.
Share financial records through your lender’s secure document portal. Ask for the exact checklist for your program so you do not have to guess which screenshots or statements are sufficient.
Connect your financing plan to the San Francisco home search
Once your budget is confirmed, compare neighborhoods and property types within it. Include property taxes, insurance, HOA dues where applicable, maintenance, and the costs of any work you expect to do. For a condo or TIC, ask your lender about the property’s financing eligibility early.
Explore the San Francisco neighborhood guide and interactive San Francisco MLS map. If your search extends down the Peninsula, our San Mateo County buying-cost guide offers another planning starting point.
Common questions about RSUs and homebuying
Can I qualify using unvested RSUs?
A future award is not the same as income already received. Fannie Mae’s cited RSU guidance requires vested, unrestricted distributions for qualifying income. Ask your lender how your specific program treats future schedules.
Do I have to sell every vested share?
Not necessarily. Income qualification and purchase funds are separate analyses. Ask which assets must be liquidated for closing and which can remain invested as acceptable reserves.
Does a larger grant immediately increase my mortgage budget?
Do not assume it does. Request an updated lender calculation based on the award’s terms and documented history before increasing your offer range.
Should I buy at my maximum approved price?
Your approval is one input. Compare the payment with your personal spending, savings goals, and a scenario with less variable compensation. Choose a search budget that gives you room to live comfortably.
Build the budget before you build the offer
I help buyers connect their financing plan with the neighborhoods, homes, and purchase strategy that fit their goals. Your lender determines qualifying income; I help turn the approved budget into a focused San Francisco or Peninsula search.
Plan your Bay Area home search Explore buyer resources →
Educational information, not individualized lending, tax, investment, or legal advice. Loan eligibility and lender requirements vary. Consult your lender and tax adviser before relying on equity compensation or selling shares. Sources reviewed October 14, 2026; verify current guidance when applying.